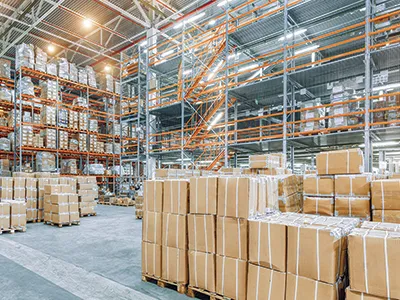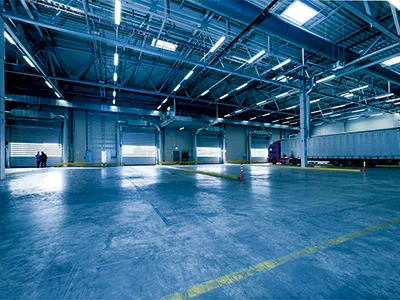
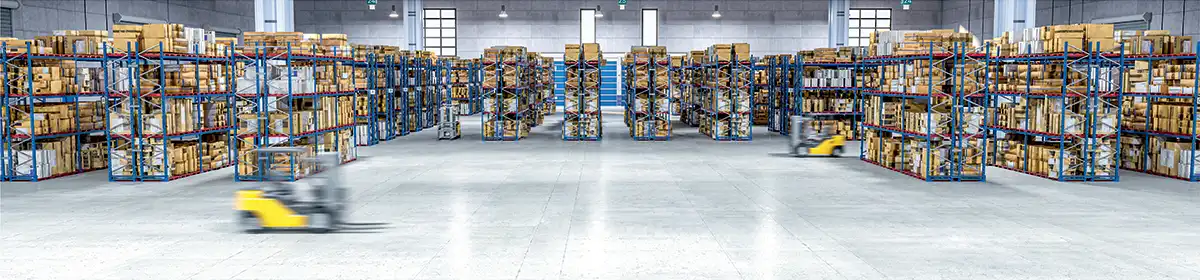
India’s warehousing sector has rapidly evolved from fragmented regional operations into a professionally managed, integrated asset class. By 2025, total stock had surpassed 610 million sq ft, with Grade A spaces accounting for 53% of supply—signaling significant quality upgrades and the growing role of institutional capital. Institutional-backed Grade A assets now make up 38% of this segment, bringing standardized development, enhanced specifications, and attracting global occupiers.
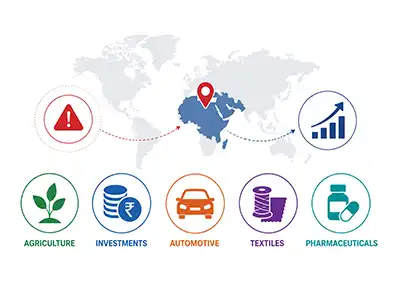
Logistics (3PL) and e-commerce continue to lead storage demand, while light manufacturing—driven by the auto, engineering, and electronics sectors—is also gaining momentum, reflecting a shift in occupier profiles.