India–UK Cargo Movement: Beyond Tariffs to End-to-End Logistics
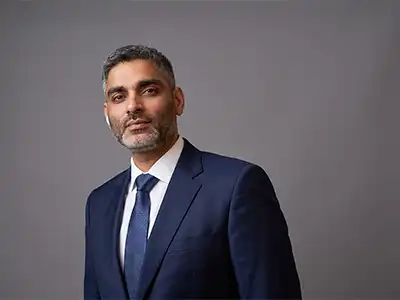
As India–UK trade ties evolve, the movement of goods between the two markets is being shaped by more than tariffs and trade agreements. Freight rates, customs procedures, documentation, last-mile connectivity and compliance continue to influence shipment costs and delivery timelines. At the same time, rising customer enquiries, expanding demand from Tier-2 cities and the growing participation of small businesses and e-commerce sellers are reshaping the logistics landscape. Asad Ali Mirza, Director, Cargo Force, examines the factors influencing the landed cost of India–UK shipments, emerging trends observed by logistics players on the ground, the operational challenges facing SMEs and e-commerce shipments, and the infrastructure and policy measures needed to support future growth.
Beyond Tariffs: The Factors Shaping Landed Costs
Honestly, tariffs are a small part of what a customer pays. On the UK–India corridor, the bigger levers are air freight rates, which move with seasonal demand and capacity, especially around Diwali; customs handling and documentation, where a single error can add days and storage charges; and the last mile, because delivering to a Tier-2 city or a family home in a smaller town costs more than a metro drop. Packaging matters too, since poorly packed goods lead to damage claims and re-handling. And compliance is often overlooked: restricted items such as lithium batteries cannot fly as cargo, and shipments held for that reason cost everyone money. Our approach is to make the price all-inclusive and to communicate clearly at every stage, from booking through weight verification to delivery, so the landed cost is known rather than discovered.
Emerging Trends: Rising Enquiries and Expanding Regional Demand
Three things. First, since the trade agreement came into force, customer enquiries have risen clearly, with people asking whether shipping to India is now cheaper or duty-free. Volumes take longer to move, and it is too early to attribute any change to the agreement itself. Second, the corridor is widening, not shifting. Metros such as Delhi, Mumbai and Bengaluru remain our backbone and are still growing, but Tier-2 cities like Ahmedabad, Jaipur, Lucknow, Kochi and Indore are the fastest-growing destinations, and that is a diaspora story before it is a trade story. Third, small businesses and e-commerce sellers are starting to use door-to-door personal cargo channels for commercial consignments, because the model is simpler than traditional freight. Over the past two years we have handled 52,000+ shipments and more than 1,500 tonnes, and the mix is visibly changing.
Operational Bottlenecks: Customs, Compliance and Shipment Visibility
For a small business, the challenge is rarely the flight. It is everything around it. Most SMEs do not have a customs broker, a compliance team or a freight desk, so documentation and classification become the bottleneck, and a wrongly declared parcel can be held or returned. Fragmented handovers are another problem: a pickup partner, an airline, a customs agent and a delivery partner, with nobody owning the outcome end to end. Visibility is the third: customers now expect e-commerce-level tracking on cargo and are frustrated when a shipment goes quiet between the airport and the doorstep. And restricted goods, particularly anything with lithium batteries, catch out new shippers regularly. The answer is a single, accountable door-to-door service with customs managed inside it, clear rules on what can travel, and tracking that updates.
Future Growth: Stronger Last-Mile Networks and Digital Integration
The biggest driver is people. Students, professionals, retirees and families moving between the UK and India, and carrying their lives with them, create steady two-way demand that trade cycles do not. Cross-border e-commerce sits on top of that, with small sellers on both sides reaching customers directly. To support it, three things matter. First, faster and more predictable customs release for low-value and personal consignments, so that the facilitation promise of the trade agreement is felt at the parcel level. Second, better last-mile infrastructure and delivery networks in Tier-2 and Tier-3 cities, where growth is fastest. Third, digital integration between carriers, customs and delivery partners, so that a shipment's status is shared across the chain rather than re-keyed at every step. Get that right, and the corridor grows on its own.